Bankruptcy Costs, Chapter 13, Chapter 7

How Much Does It Cost to File Bankruptcy in Florida?

Bankruptcy filing costs depend largely on whether you file under Chapter 7 or Chapter 13 and whether you hire an attorney.

Some people choose to represent themselves because they believe they cannot afford an attorney.

Filing for bankruptcy pro se can be risky because the process involves complex rules, forms, statutes, and court decisions.   Most people end up hiring aan attorney to navigate the legal process.

Attorney Fees

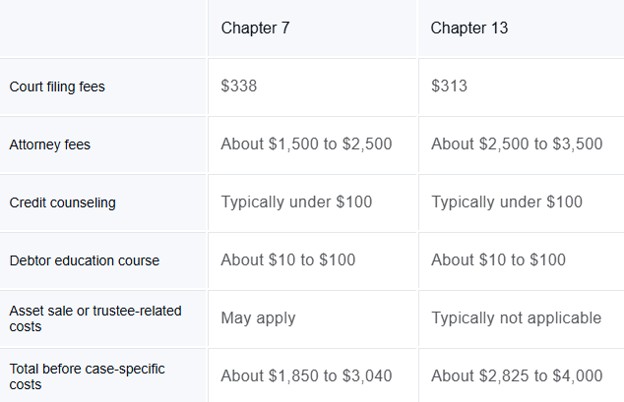
While some attorneys charge a flat rate for bankruptcy services, others charge an hourly rate. In general, Chapter 7 filers pay about $1,500 to $2,500 in attorney fees upfront, while Chapter 13 filers often pay about $2,500 to $3,500, with higher costs possible depending on location and case complexity. Chapter 13 fees are usually built into your monthly debt repayment plan.

If your case involves a business, significant property, disputed debts, or other complications, it may require more attorney time and result in higher fees. Chapter 13 cases cost more because they require attorneys to develop a repayment plan and often involve additional work over the course of the case.

While these costs are high, hiring an attorney ensures that your dischargeable debts are managed correctly.

Chapter 7 vs. Chapter 13 filing fees

The cost of bankruptcy includes separate court and attorney fees. At a minimum, every filer must pay court filing fees directly to the bankruptcy court, along with credit counseling costs.

The basic court fees for Chapter 7 and Chapter 13 break down as follows:
Additional Court Fees

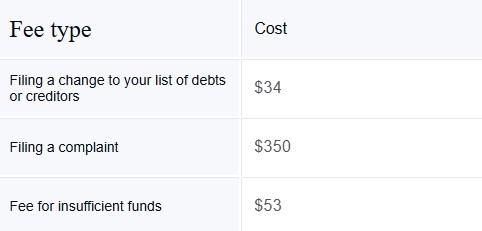
The U.S. Courts may charge for specific services throughout your case. The following table outlines common administrative fees accurately as of publication but note that this list is not exhaustive of every fee you might encounter.
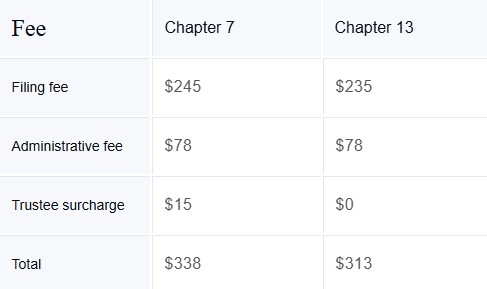
Chapter 7 filers who meet income requirements and cannot afford installments may ask the court to waive the filing fee. This option is available to those earning less than 150% of the federal poverty level. Chapter 13 fees cannot be waived, but eligible filers may request an installment plan.

Basic filing fees may not cover all court-related expenses. Additional services and actions during a bankruptcy case can add to the total cost.
Additional costs of filing for bankruptcy

In addition to court and attorney fees, bankruptcy may involve smaller required or case-specific expenses. Although these costs are usually modest, they can still strain an already tight budget:

  • Credit counseling fees: You are typically required to attend at least one credit counseling session before filing. You can work with a credit counselor or take an online class, and classes usually cost under $100. The U.S. Department of Justice maintains a list of approved agencies you can use.
  • Debt education course: After filing, you must complete a financial management Depending on the provider, it can cost $10 to $100.

Click here to read more.

If you have questions on this topic or are in a financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can assist you and address all your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild, and recover. The day you hire our firm; we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Bankruptcy Law, Consumer Bankruptcy

What Assets Can Creditors Seize in Bankruptcy?

Bankruptcy filers often fear losing everything they own when going through a Chapter 7 or Chapter 13 bankruptcy case. You may think that filing for bankruptcy means you have to give up your home, your car, and other important assets.  This is simply not true. Laws are in place to help protect you, while also providing creditors with a portion of debt repayment.

All nonexempt assets may be used to repay your creditors in a Chapter7 bankruptcy. These include:

  • Vehicles
  • Land
  • Houses
  • Investment Properties
  • Items of value, like jewelry artwork.

However, many Chapter 7 cases are no-asset cases, meaning the debtor gives up no possessions. This happens for two reasons. First, you can allot for basic assets, called exemptions that are necessary for day-to-day living.  For example, the homestead exemption that protects your primary residence. Your vehicle that you need to get to and from work. Personal items and household goods, tools of the trade (i.e. – items you own and use to make a living) are all protected.

The U.S. Bankruptcy Code and Florida bankruptcy laws protect a great deal of a consumer’s property, if used appropriately. The State of Florida has some of the most generous bankruptcy exemptions in the country, but these exemptions only apply to individuals who meet certain residency requirements. For these exemptions to apply, the consumer must have lived in the state for at least two years before filing. Otherwise, federal exemptions apply.

Click here to read more.

If you have questions on this topic or are in financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can advise you of all of your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild and recover. The day you hire our firm, we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Bankruptcy Law, Consumer Bankruptcy

What Documents do you need to File Bankruptcy in Florida?

At the start of a bankruptcy case, the filer is asked to fill out certain documents, including disclosures regarding the person’s financial affairs. This disclosure includes the person’s income, expenses, assets, debts, and any property transfers.

The filer will also need to provide supporting documentation, and the documents required are essentially the same for both Chapter 7 and Chapter 13 cases, with slightly different variations. It is often helpful to check with the bankruptcy trustee to ensure that all required documentation is submitted. Some trustees require more proof than others, and many times, this evidence will also be determined by the facts of the individual’s case.

Bankruptcy Trends

Consumer Bankruptcy Filings Increase in August

Bankruptcy filings increased in the month of August for all chapters of consumer bankruptcy cases, according to a new study conducted by Epiq. A total of 35,355 bankruptcy filings were reported in August, which represents a 10 percent increase from the total of 32,276 reported in August 2021.

Commercial bankruptcy filings also increased by six percent in August. A total of 1,861 filings were made in August 2022, as compared to the 1,753 cases filed in August 2021. Individual bankruptcy filings increased by 10 percent. A total of 33,494 filings were made in August 2022 and 30,523 were filed in August 2021.

Bankruptcy Law, Consumer Bankruptcy

Do I need a lawyer to file bankruptcy in Florida?

Filing for bankruptcy can be an uncertain and intimidating process. Going through it alone can make the process that much more daunting. While an attorney is not a requirement for filing for bankruptcy, it certainly helps ensure that a bankruptcy case proceeds smoothly.

A bankruptcy attorney will meet with the client first during a consultation to discuss the person’s financial situation to determine whether he or she needs to file for bankruptcy. Occasionally, it can be in the client’s best interest to wait before filing, but he or she may not realize that until talking through the situation with an attorney.

Consumer Bankruptcy, Legal Awards

Miami Bankruptcy Attorney Timothy S. Kingcade Named a Florida Super Lawyer 8 Consecutive Years

Managing Shareholder, Timothy S. Kingcade of the Miami-based bankruptcy and foreclosure defense law firm of Kingcade Garcia McMaken has been selected for inclusion in Florida Super Lawyers 2021, in the practice area of consumer bankruptcy. This is the eighth consecutive year Kingcade has been selected to the Florida Super Lawyers list (2014-2021). The prestigious honor is awarded to only five percent of lawyers in the state.

After receiving one of the highest point totals, Kingcade was also selected to be on the Florida Super Lawyers Blue Ribbon Panel. Only those in each practice area with the highest point totals are asked to be part of the panel to evaluate the candidacy of fellow lawyers to enter the prestigious Super Lawyer rankings.

Bankruptcy Law, Consumer Bankruptcy

The Cost of Filing Bankruptcy in 2021

Filing for bankruptcy comes with its own set of costs. It may seem counterintuitive that a person who is having difficulty paying his or her bills can pay extra costs to receive relief from his or her financial obligations. However, just because someone is not able to pay his or her bills should not prevent them from hiring an attorney to file their bankruptcy case. While “do it yourself” projects may be a good idea around the house, there are reasons to let a professional handle your bankruptcy filing.

Bankruptcy Law

Knowing When to File for Bankruptcy

Making the decision to file for bankruptcy is never an easy one. Many times, it can be difficult to know when the time is right or when it is better to wait.  

A bankruptcy case allows a consumer to receive a much-needed financial fresh start by discharging his or her outstanding consumer debts. The types of debts that are discharged in a bankruptcy case include credit card debt, mortgages, car loans, medical debt, and other unsecured loans.  

Bankruptcy Law

What is a ‘No Asset’ Chapter 7 Bankruptcy Case?

In a no-asset Chapter 7 bankruptcy case, the person filing for bankruptcy keeps all of their property because it falls within the exemptions provided under federal law or the law in their state.

With a Chapter 7 liquidation bankruptcy, a filer surrenders their assets to the bankruptcy estate, which uses them to pay off creditors. But in reality, this is only true of non-exempt property. Many of our cases, are in fact, ‘no asset’ cases. Bankruptcy law recognizes that filers need to retain some property so they can survive the process with something on which to build a future after bankruptcy.

Bankruptcy Law

How Will Filing For Bankruptcy Affect My Spouse?

Filing for bankruptcy when someone is married can be a joint process, or it can be done by only one spouse proceeding with the case. Ultimately, it depends on the type of debt and the financial situations for both spouses. For example, if one only spouse owes a specific debt or debts, then that spouse may be able to proceed on a bankruptcy alone, especially if the other spouse has good credit and very few other debts. Proceeding with a single bankruptcy case while married can be complicated, and in certain situations, it can adversely affect the non-filing spouse, but not always.  

Joint Debts

In any marriage, parties bring in their own, individual debts, and debts are almost always incurred during the marriage, as well. One spouse may choose to take out a loan, not naming the other spouse on the debt, which means only the spouse whose name is on the debt is responsible for what is owed. If that spouse is not able to continue making payments on the debt, he or she can proceed with a bankruptcy to discharge that debt. If the debts listed in that bankruptcy case belong to the filing spouse alone and not the non-filing spouse, discharging the filer’s debts and liabilities should be a straightforward process. It becomes more complicated if any of the debts listed in the bankruptcy case belong to the non-filing spouse. In these situations, these joint debts will normally remain with the non-filing spouse.