Bankruptcy Costs, Chapter 13, Chapter 7

How Much Does It Cost to File Bankruptcy in Florida?

Bankruptcy filing costs depend largely on whether you file under Chapter 7 or Chapter 13 and whether you hire an attorney.

Some people choose to represent themselves because they believe they cannot afford an attorney.

Filing for bankruptcy pro se can be risky because the process involves complex rules, forms, statutes, and court decisions.   Most people end up hiring aan attorney to navigate the legal process.

Attorney Fees

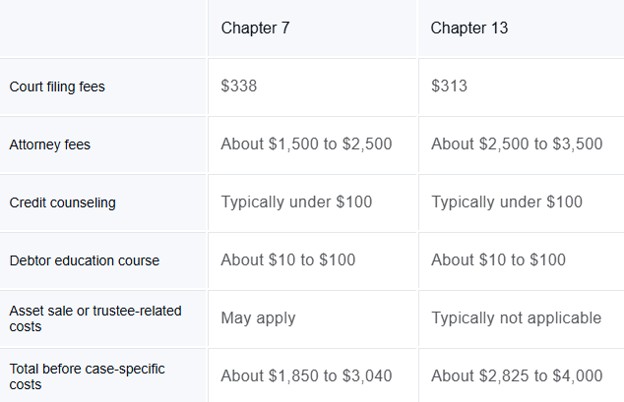
While some attorneys charge a flat rate for bankruptcy services, others charge an hourly rate. In general, Chapter 7 filers pay about $1,500 to $2,500 in attorney fees upfront, while Chapter 13 filers often pay about $2,500 to $3,500, with higher costs possible depending on location and case complexity. Chapter 13 fees are usually built into your monthly debt repayment plan.

If your case involves a business, significant property, disputed debts, or other complications, it may require more attorney time and result in higher fees. Chapter 13 cases cost more because they require attorneys to develop a repayment plan and often involve additional work over the course of the case.

While these costs are high, hiring an attorney ensures that your dischargeable debts are managed correctly.

Chapter 7 vs. Chapter 13 filing fees

The cost of bankruptcy includes separate court and attorney fees. At a minimum, every filer must pay court filing fees directly to the bankruptcy court, along with credit counseling costs.

The basic court fees for Chapter 7 and Chapter 13 break down as follows:
Additional Court Fees

The U.S. Courts may charge for specific services throughout your case. The following table outlines common administrative fees accurately as of publication but note that this list is not exhaustive of every fee you might encounter.
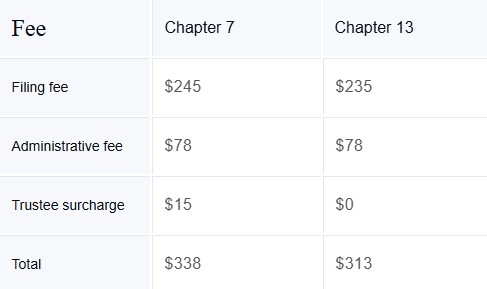
Chapter 7 filers who meet income requirements and cannot afford installments may ask the court to waive the filing fee. This option is available to those earning less than 150% of the federal poverty level. Chapter 13 fees cannot be waived, but eligible filers may request an installment plan.

Basic filing fees may not cover all court-related expenses. Additional services and actions during a bankruptcy case can add to the total cost.
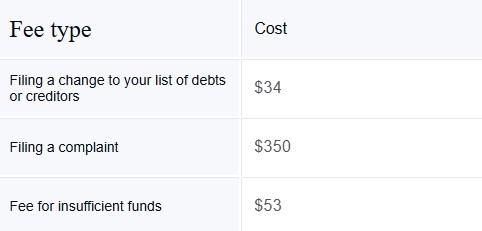
Additional costs of filing for bankruptcy

In addition to court and attorney fees, bankruptcy may involve smaller required or case-specific expenses. Although these costs are usually modest, they can still strain an already tight budget:

  • Credit counseling fees: You are typically required to attend at least one credit counseling session before filing. You can work with a credit counselor or take an online class, and classes usually cost under $100. The U.S. Department of Justice maintains a list of approved agencies you can use.
  • Debt education course: After filing, you must complete a financial management Depending on the provider, it can cost $10 to $100.

Click here to read more.

If you have questions on this topic or are in a financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can assist you and address all your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild, and recover. The day you hire our firm; we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Credit Card Debt

Americans Are Falling Behind on their $1.25 Trillion Credit Card Debt

How much is too much credit card debt?

Surging inflation and rising interest rates have left millions of Americans relying on credit cards to cover everyday expenses. Middle-class households are struggling the most to pay down these balances. More families have shifted to a pattern of “survival debt.” Survival debt refers to money borrowed explicitly to cover basic, essential living expenses, like food, housing, utilities, and medical expenses, rather than discretionary purchases.

America’s credit card balance is a staggering $1.25 trillion, up from $1.18 trillion in the same quarter last year. The average interest rates on credit cards rose to 21% in February, from 14.6% in February 2022, according to a survey by the Federal Reserve.

With the rising cost of food, housing, and healthcare there is less money to pay down credit card debt. Consumers have been forced to make some tough decisions. Not wanting to lose their car or their home, people are likely to stop paying their credit cards, first.

Credit counseling agencies have seen an uptick in clients by 60%, since 2018. The National Foundation for Credit Counseling, a network of nonprofits that helps people reduce credit-card debt, said it had 24% more clients in January than a year earlier.

People carry an average of about $6,500 to $6,700 in credit card debt, according to credit-reporting agencies. The percentage of cardholders with balances of more than $10,000 has risen in communities across different income levels since 2018, analysis from the Urban Institute data shows. Last year, 17% of cardholders in low-income communities held balances greater than that amount, 20% in medium-income communities and 25% in higher-income communities.

While each consumer’s financial situation is different, there are ways to determine if you are carrying too much credit card debt.

Consider your answers to the following questions:

  • Is your credit card debt impacting your financial and emotional health? Carrying large amounts of credit card debt can damage your credit score and cause you to experience financial and emotional stress. A good rule of thumb is to ensure your monthly payments are not more than 10 percent of your monthly income.
  • Are you paying only the minimum? Credit cards typically have low monthly minimum payments, but that doesn’t mean they are affordable just because you can cover that amount. If you are only able to make the minimum payment, that can be a sign you have too much credit card debt.
  • Is your credit card debt impacting your credit score? Credit cards can help your credit score- or hurt it, depending on how you use them. It is recommended that you keep your credit utilization below 30 percent. Having significant credit card debt can have a negative impact on your credit score. This can make other debts, like your mortgage and car payments more expensive.

As bankruptcy attorneys, we see credit card debt as one of the most common problems facing those with serious financial challenges.

Filing for bankruptcy is a viable option for those struggling with insurmountable credit card debt. Chapter 7 is the fastest form of consumer bankruptcy and forgives most unsecured debts like credit card debt, medical bills, and personal loans.  There are certain qualifications a consumer must meet in regard to income, assets, and expenses to file for Chapter 7 bankruptcy, which is determined by the bankruptcy means test.

Click here to read more on this story.

Bankruptcy Law

What is the 180-day Rule in Bankruptcy?

When it comes to filing bankruptcy in Florida, timing matters. Aside from things like income limits, exemptions, and credit counseling requirements, the timing of your bankruptcy filing can either protect you or put you at risk. Let’s say, your paycheck arrives late. A tax refund hits your account. A family member passes away and leaves you inheritance money. Any of these events can affect how your bankruptcy case unfolds.

The 180-day rule is a bankruptcy provision that determines whether certain benefits or assets obtained within 180 days after filing must be included in your bankruptcy estate. This means if you file for bankruptcy and then receive or inherit certain types of money within the next 180 days (about 6 months), the bankruptcy court may treat that money as if you had it when you filed. This rule most commonly applies to:

  • Inheritances
  • Life insurance proceeds
  • Property settlements from divorce or separation
  • Certain trust distributions

If any of these occur within 180 days after your filing date, the assets could potentially be used to repay your creditors. This surprises many filers because they assume only assets owned on the filing date matter. The 180-day rule extends that window, making timing crucial.

How Does the 180-day Rule Affect Chapter 7 vs. Chapter 13?

Chapter 7 bankruptcy: Because Chapter 7 involves, liquidating non-exempt assets, anything covered by the 180-day rule could be taken by the bankruptcy trustee and distributed to creditors. For example, receiving an inheritance three months after filing could mean losing part or all of it.

Chapter 13 bankruptcy: In Chapter 13, you commit to a repayment plan and keep your assets. Assets acquired under the 180-day rule may increase how much you are required to repay over the life of your plan.

What does the 180-day rule not cover?

The 180-day rule does not apply to everything acquired. For example:

  • Regular wages earned after filing are generally protected
  • Bonuses tied to post-filing work are usually excluded
  • Tax refunds depend on when the income was earned, not when the refund arrives

That distinction is why professional guidance matters when it comes to navigating a bankruptcy.  If you have questions on this topic or are in financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can advise you of all of your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys’ help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild and recover. To learn more, visit the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Source: What is the 180-day rule in bankruptcy? – CBS News

Bankruptcy Law, Consumer Bankruptcy

How Much Debt Do You Have to Have to File Bankruptcy?

When it comes to filing Chapter 7 bankruptcy, the filer must meet a certain threshold when it comes to his or her debt-to-income ratio and qualify under the means test. However, there is no requirement that the filer carry a certain amount of debt to file Chapter 7 bankruptcy.

Federal bankruptcy law dictates the eligibility requirements to file Chapter 7 bankruptcy. The biggest of these requirements is the means test which compares the filer’s income to his or her debt. The means test is a two-step process. The first step requires looking at the consumer’s income as compared to Florida’s average income. If the filer’s income is higher than the median income for a household in Florida, the filer will need to then take the second part of the means test.

Debt Relief

What is Debt Relief and When Should I Seek It?

Debt can seem like an insurmountable burden, impossible to escape once a consumer has gotten too far in. Different options are available for dealing with credit card debt, student loan debt, and other consumer debts.  

Many times, consumers find themselves overwhelmed with several different types of debt in differing amounts.

Bankruptcy Law

The Pre-Bankruptcy Credit Counseling Requirement and What Filers Need to Know

All bankruptcy filers are required to take and complete two educational courses before receiving a final bankruptcy discharge. These courses are required for both Chapter 7 and Chapter 13 filers. It is important that individuals considering bankruptcy be aware of these requirements for their cases to be successful.  

At the start of a bankruptcy case, the individual filing must meet certain requirements. The filer must disclose his or her complete financial picture by submitting required bankruptcy financial declarations. He or she must also pay a filing fee, request a fee waiver, or request an installment payment for the fee. Lastly, the individual must submit proof that he or she received credit counseling from an agency approved by the U.S. Trustee’s office. This proof of completion must show that the course was taken within 180 days prior to filing.

Debt Relief

Credit Counseling vs. Bankruptcy- Which one is right for you?

When it comes to dealing with debt, you have options.  Debt relief can ease the burden of overwhelming debt, but it’s not right for everyone. Given a person’s financial and personal circumstances, certain considerations should be kept in mind when making the determination between credit counseling and bankruptcy.

If the consumer has a steady income and can pay back his or her debt within a few months to a year, credit counseling may be the wise choice for him or her. However, if the person has an overwhelming amount of debt in comparison to his or her income, filing for Chapter 7 or Chapter 13 bankruptcy may be the better option.  

Credit Card Debt, Debt Relief

Credit Card Debt Can Be Bad for Your Health, According to Recent Study.

Having large amounts of credit card debt can not only stress you out, but according to a new study it can also be bad for your health. The high levels of stress associated with the debt can get so serious that it can adversely affect the person’s health, according to a study from CompareCards.com.

According to the report, fewer cardholders can pay their balances in full at the end of each month. Anything left on those balances roll over to the next month and are compounded even more by interest. Before long, those balances inch closer and closer to the maximum balance allowed. One in three consumers surveyed by WalletHub reported being fearful that they will max out their credit cards when making a large purchase. Most of those polled said they considered a large purchase was anything more than $100.

Bankruptcy Law

What are the Credit Counseling Requirements in Bankruptcy?

Whenever a person files for Chapter 7 or Chapter 13 bankruptcy, he or she must submit proof that a credit counseling course from a nonprofit credit counseling agency was successfully completed. The purpose of this course is to help the filer determine whether he or she can pay his or her debt outside of bankruptcy and provide proper financial guidance to prevent an additional bankruptcy filing in the future.

What Is Required?

According to the Federal Trade Commission (FTC), all bankruptcy filers must take an approved credit counseling course prior to filing. The U.S. Department of Justice’s U.S. Trustee Program keeps a list of approved programs if filers are not sure where to go. Proof of completing a program must be submitted before the bankruptcy case can proceed further. In fact, this proof must be submitted within 180 days prior to filing for bankruptcy. The filer will normally walk away from the credit counseling program with a repayment plan, if a plan is realistic, although nothing in the FTC rules requires the filer to follow that specific plan.

Bankruptcy Law, Credit Card Debt, Debt Relief, Timothy Kingcade Posts

The Top Ways To Get Out Of Debt

Debt is a weight that can drag you down and make you feel like you are drowning without any way out.  Having extreme debt can affect your health, happiness and personal relationships.  Getting out of debt can be an even bigger struggle, if you do not devise a plan that works for your specific situation.

Debt Consolidation

One popular method of paying off debt is through debt consolidation. What consolidation means is the consumer’s debt is combined into one, single debt amount owed. Debt consolidation can be done through many different methods. A consumer can apply for a personal loan or consolidation loan to pay off all of the debts with the monies from the loan. This method allows you to only make one payment to one creditor rather than multiple creditors.  With this method, we strongly advise that you do your research. Not all debt consolidation companies are reputable, and it is important you understand the terms of the loan before signing on the dotted line. For most debt consolidation loans, you need good credit to be approved. If you are already struggling financially, many lenders will see you as a risky bet and will avoid lending to you without a co-signer or at least some collateral to secure the debt.

Credit Counseling

Many different credit counseling resources exist, and they usually involve a professional counselor who will work with the debtor on understanding his or her financial situation and researching possible options to get out of debt. Credit counselors often will work with the individual to organize and manage their debt, and the counselor will also contact the debtor’s creditors on payment arrangements, including creating payment plans or negotiating lower interest rates. Credit counselors can also put together a debt management plan that allows the debtor to make lower monthly payments through the debt counselor who, in turn, pays the individual’s creditors.

Like debt consolidation companies, it is important that you do your due diligence in choosing a credit counselor. Less-than-reputable agencies do exist, so make sure you choose someone who has your best interests in mind. Know that a credit counselor cannot make certain promises, such as guaranteeing that your creditors will work with them or that they will be able to directly reduce your debt. While they can certainly work towards that goal, lenders are not obligated to work with credit counselors. If a ‘credit counselor’ is promising you this or telling you that they can completely eliminate your debt by having you pay a low monthly payment to them, this is a BIG red flag.

Debt Settlement

Another potential option for paying off debt is through debt settlement. This process normally involves a third-party company that works with a debtor’s creditors to allow the debtor to pay a lower amount than what is owed. However, with this option the likelihood of scams is very high. Many of these companies have been reported for taking the debtor’s money and never negotiating on the debt. Additionally, debt settlement can result in a person’s credit taking a rather serious hit due to the fact that the debtor will normally have to stop making payments to the creditor, pushing the accounts into default. Unless the creditor agrees to work with the debt settlement company, a judgment can easily be issued against the debtor, resulting in wage garnishment to satisfy the debt.

Filing for bankruptcy

Debt can be complex and oftentimes frightening to deal with. Many times, people are hesitant or feel ashamed to ask for help. However, not properly dealing with debt can only make problems worse. Rather than run the risk of being sued by a creditor or have your wages garnished, it is best to deal with your debt head on. There are a number of debt relief options available, including filing for bankruptcy, which can completely wipe out unsecured debts like credit cards, medical bills, personal loans and more- and give you a fresh financial start. Exploring these options with the guidance and support of an experienced attorney can help you make the right decision.

Do not let your debt cost you another sleepless night. Here are some of the signs that bankruptcy is right for you. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys’ help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild and recover. The day you hire our firm, we will contact your creditors to stop the harassment. The consultation is free, the relief is real! You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.