Credit Card Debt

Four Ways to Get out of Credit Card Debt

Credit cards are among the most expensive ways to borrow- especially these days. The Federal Reserve’s war on inflation, marked by interest rate hikes, has lifted credit card rates to record highs. According to a recent NerdWallet American Household Credit Card Debt Study, the average amount of revolving credit card debt owed per American household is $7,486. Getting out of this debt can be difficult, but it is not impossible with proper planning. The following strategies are proven to be successful when getting out of credit card debt.

Determine a Payment Strategy

The first step to paying down credit card debt is to determine what type of payment strategy would work best for the consumer.  Paying more than the minimum monthly payment posted is always the best place to start since the monthly minimum payment is normally only two percent of the balance and pays more for interest accrued every month than the principal owed.
Credit Card Debt

How to Respond If You Are Sued for Credit Card Debt

Most consumers utilize a credit card at some point in their lives, and many of them carry credit card debt from month-to-month. The amount of credit card debt carried by consumers is growing. It is estimated that around 23.5 percent of all Americans struggle with some type of debt in collections status, according to the Consumer Financial Protection Bureau (CFPB), and much of this debt involves credit card debt. If a consumer is on the receiving end of a collections lawsuit for credit card debt, it is important to know how to respond.

A collections lawsuit can vary, depending on the jurisdiction, but, the steps are all fairly uniform. The first thing to expect is the consumer will receive a complaint filed in civil court, along with a summons. This summons should contain a number of important pieces of information including who is suing the consumer, whether any additional co-defendants are a part of the lawsuit, how much money the creditor is attempting to seek, which can include the balance owed, along with interest fees and legal fees, the date of the hearing, and how to file a formal answer or response to the complaint.

Credit Card Debt

Credit Card Study Reports These States Have the Highest Credit Card Debt Increases

Credit card spending among American consumers has hit a high of $1.2 trillion with $116 billion of this balance added during 2023 alone. Some areas of the country are adding to this debt balance more than others with California, Texas, and Florida being at the top of the list.

WalletHub recently conducted a study of all 50 states, using data reported from TransUnion and the Federal Reserve, adjusted for inflation. They found that certain areas of the country have been contributing significantly to the current national credit card debt while others have been contributing significantly less.

Consumer News, Credit Card Debt

Credit Card and Car Loan Defaults Hit 10-Year High

A number of consumers are defaulting on their credit cards and car loans to the point where the number of defaults reported are the highest seen since the financial crisis. With inflation not nearing an end any time soon and interest rates continuing to rise, the number of consumers defaulting is expected to grow.

This information comes from data provided by the credit agency, Equifax. The agency found that credit card delinquencies have hit 3.8 percent while car loan defaults have hit 3.6 percent. These figures are the highest ones seen in more than 10 years.

Credit Card Debt

Credit Card Debt Tops $1 Trillion

Total credit card debt reached $1.03 trillion in the second quarter of 2023, according to the Federal Reserve Bank of New York.  That’s a 5% increase, or about $45 billion in consumer credit card debt. With student loan payments resuming in the fall, this can present challenges for borrowers going forward.

Not only are credit card balances higher, but more cardholders are also carrying debt from month-to-month, according to a separate Bankrate report, adding to the financial stress. Another rate hike by the Federal Reserve, which occurred last month, made the average credit card rate over 20%.

Medical Debt

Medical Credit Cards Drive Patient Debt and Inflate Costs of Health Care, according to CFPB Report

The Biden administration has issued a word of caution to consumers about the growing concerns they have behind medical credit cards and other loans used to pay down medical bills. These concerns have been expressed in a new report published, which warns consumers that high interest rates on these cards can only increase the patient’s debt and eventually threaten their financial situation.

In the report, issued by the Consumer Financial Protection Bureau (CFPB), they reported that U.S. consumers paid $1 billion in deferred interest on medical credit cards and other types of medical financing between the years 2018 and 2020. The interest rates on these cards can be particularly high, which is why the CFPB found that medical credit card interest rates can inflate medical bills by approximately 25 percent (25%).

Credit Card Debt

Consumers Add a Record $179.4 Billion in Credit Card Debt

U.S. consumers have hit a record high when it comes to credit card debt. According to a recent WalletHub study, American consumers added a record $179.4 billion in new credit card debt to the already-existing credit card debt in 2022. These numbers are expected to increase as we move into the second half of 2023.

The largest increase was seen in the fourth quarter of 2022 with an increase of $84.9 billion in that quarter alone. A fourth-quarter increase is not unusual, as it is usually followed by a first quarter pay-down. However, once 2023 began, WalletHub found that American consumers only paid down their credit card debt by $24 billion, which is the second smallest first-quarter credit card debt paydown seen in the last decade.

Credit Card Debt, Credit Score

How Credit Card Debt Impacts Your Credit Score

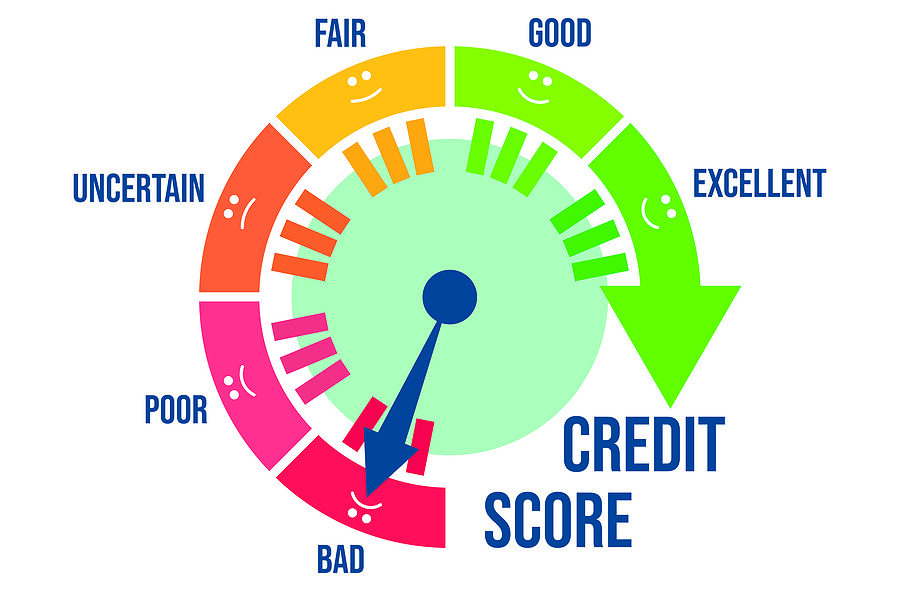
Most consumers utilize a credit card at some point in their lives, and many of them carry credit card debt from month-to-month. While using credit cards responsibly can help increase a person’s credit score, having too much credit card debt can cause significant harm to that score.

The amount of debt you owe on your credit card is one of the biggest factors affecting your credit score. That’s why it is never a good idea to max out your credit card. And when your credit score goes down, you could end up having to pay higher interest rates on loans or any other credit you apply for. A low credit score can impact your applications for apartment rentals, cell phone plans, and more. Research by the Consumer Financial Protection Bureau has indicated that high income earners are as prone to financial stress because of debt as low-income earners.

Bankruptcy Trends, Consumer Bankruptcy, Consumer Debt

Five Reasons People Go Bankrupt

The number of bankruptcy filings across the U.S. are on the rise. Common reasons that people file for bankruptcy include loss of income, medical bills, a mortgage payment that is too high, spending beyond their means, or lending money to loved ones.

Many times, it is not just one simple cause, but rather a combination of factors that contribute to why someone has filed for bankruptcy. Here are some common reasons people file bankruptcy.