Bankruptcy Filings, student loan debt, Student Loans

Student Loan Overhaul Could Lead to More Bankruptcy Filings, Says Judge

After nearly three decades as a bankruptcy judge, Sarah Sharer Curley details what she calls the unfairness of the legal process in her new book, “The Price of Forgiveness: Debt, Bankruptcy, and the Future of Fairness in America.”

She calls Trump’s “Big Beautiful Bill” an “attack” on student loan borrowers and predicts an increase in bankruptcy filings. She says the law sets unrealistic federal student loan caps, potentially pushing students toward private loans that lack federal guarantees and often carry higher interest rates.

For example, let’s say a student needs a $300,000 loan to go to medical school. If the individual has a lower credit score, their interest rate may jump to 16%, leading to a payment of $5,017 per month over 10 years, or $302,040 in interest.

These expenses are not sustainable for most individuals. The rate of bankruptcy filings will most likely increase. One of the most painful cases she witnessed in her three decades presiding over bankruptcy cases, involved a 73-year-old woman who stood before her in 2012 with a student loan balance of more than $584,000.

The debt dated back to the 1970s and had grown throughout the woman’s public sector career. She had “never made a lot of money,” Curley said, and by the time she sought debt relief, the woman was living in poverty, with Social Security as her only income. Even so, strict bankruptcy laws can make student loans nearly impossible to discharge.

There were attempts by the U.S. Department of Education to work out repayment plans for student loan borrowers who could not repay their debts. There was also the possibility that the Education Department would agree to forgive at least a portion of the student loans.

However, once the Education Department was gutted in 2025, there were few, if any, employees who could approve the debt modifications through one of the offered programs. As a result, it has become harder to reach a settlement with the Department of Education.

In 2025, more than half a million personal bankruptcy cases were filed — an almost 50% rise from three years prior, according to the Administrative Office of the U.S. Courts.

Click here to read more.

For borrowers who are struggling with student loan debt, relief options are available.  Many student loan borrowers are unaware that they have rights and repayment options available to them, such as postponement of loan payments, reduction of payments or even a complete discharge of the debt. There are ways to file for bankruptcy with student loan debt.  It is important you contact an experienced Miami bankruptcy attorney who can advise you of all your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild, and recover. The day you hire our firm; we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Filing Bankruptcy, Life After Bankruptcy, Rebuilding Credit

What Happens After Bankruptcy?

After filing for bankruptcy, you will likely have questions about how it will affect your credit and what steps you can take to move forward.

What can I expect the first year after filing bankruptcy?

A bankruptcy discharge releases you from personal liability for qualifying debts. In Chapter 7, you can be free and clear of your debts within a few months after filing; in Chapter 13, it generally comes after you complete the repayment plan.

Prioritizing your financial stability should be a top priority one year after filing. Avoid taking on any new debt. Many people receive credit card offers in the mail soon after filing bankruptcy. And while it can be tempting, it’s best to avoid these offers. Instead, focus on managing your monthly expenses, building an emergency fund, and reducing any major expenses.

A reason people hold off on filing bankruptcy is the fear of what it will do to their credit and financial future. While filing for bankruptcy will impact a person’s credit score, this damage is not irreparable.

After bankruptcy, you can begin taking steps right away to improve your credit history.

  1. Pull a copy of your credit reports for free by visiting https://www.annualcreditreport.com/.
  2. Make sure your credit reports are accurate. The accounts that were discharged in bankruptcy should be closed. If any discrepancies are found, these errors should be reported right away to the credit bureaus via a formal dispute.
  3. Prioritize making future payments on time. It sounds simple, but on-time payments and responsible credit card use can significantly help you recover from bankruptcy.
  4. Open a new line of credit. After some time has passed and you feel financially stable, consider opening a new line of credit with a reputable lender to reestablish healthy credit habits.
  5. Creating a budget is important after completing a bankruptcy case. Write down all necessary living expenses and track how much of the consumer’s income can be used to go towards paying these costs. A good rule of thumb when budgeting is to follow the 50/30/20 rule. What this entails is 50 percent of the consumer’s income goes towards meeting his or her needs. Another 30 percent would be set aside for items that are considered not necessary or are wanted, while 20 percent of the monthly income goes towards savings.

Click here to read more.

Facing financial hardship and considering bankruptcy? An experienced Miami bankruptcy attorney can guide you through the process. Timothy Kingcade combines his experience as a CPA and bankruptcy lawyer to help clients protect their assets and achieve successful results under bankruptcy law. Since 1996, Kingcade Garcia McMaken, P.A., has helped people from all walks of life build a brighter future. Each year, our firm helps thousands of people use bankruptcy protection to restart, rebuild, and recover. We contact your creditors the day you hire us to stop the harassment. Find more consumer information at www.miamibankruptcy.com.

Foreclosure Defense, Foreclosures

These 2 Southern States Lead the Nation with the Highest Number of Foreclosures

Foreclosure rates have been on the rise, signaling homeowners are struggling with the cost of homeownership.  There was a total of 36,033 U.S. properties with foreclosure filings, up 0.4% from the prior month and 13.9% from a year ago, according to the U.S. Foreclosure Market Report from ATTOM.

The report revealed that Florida, South Carolina, and Illinois had the worst foreclosure rates in the nation.

High foreclosure rates can be attributed to a range of factors, including economic pressure, local housing market dynamics, and state-specific foreclosure procedures. Of the three states, only Florida, with a median home list price of $440,000, is above the national median at $431,250.

The report revealed that two-thirds of the 50 counties around the U.S. considered most exposed to potential fallbacks were in Florida, California, Illinois, and the New York region.

South Carolina saw 1 in every 2,311 housing units with a foreclosure filing; Illinois had 1 in every 2,405 housing units; and Florida had 1 in every 2,526 housing units.

Among those major metropolitan statistical areas with a population of at least 200,000, those with the greatest number of foreclosure starts in April 2025 included Houston (1,202), Chicago (1,139), New York City (1,099), Miami (739), and Atlanta (665).

Click here to read more.

Choosing the right attorney can make the difference between keeping your home or losing it in foreclosure. A well-qualified Miami foreclosure defense attorney will not only help you keep your home, but they will be able to negotiate a loan that has payments you can afford. Miami foreclosure defense attorney Timothy Kingcade has helped many facing foreclosure alleviate their stress by letting them stay in their homes for at least another year, allowing them to re-organize their lives. If you have any questions on the topic of foreclosure, please feel free to contact me at (305) 285-9100. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Auto Loan Debt, Consumer Debt

Auto Loan Debt Rising in the U.S. – Here are Cities with the Most

People in the U.S. collectively owe over $1.64 trillion in auto loan debt, with the average household owing nearly $14,000. These loans have become significantly more expensive, and interest rates have surged.

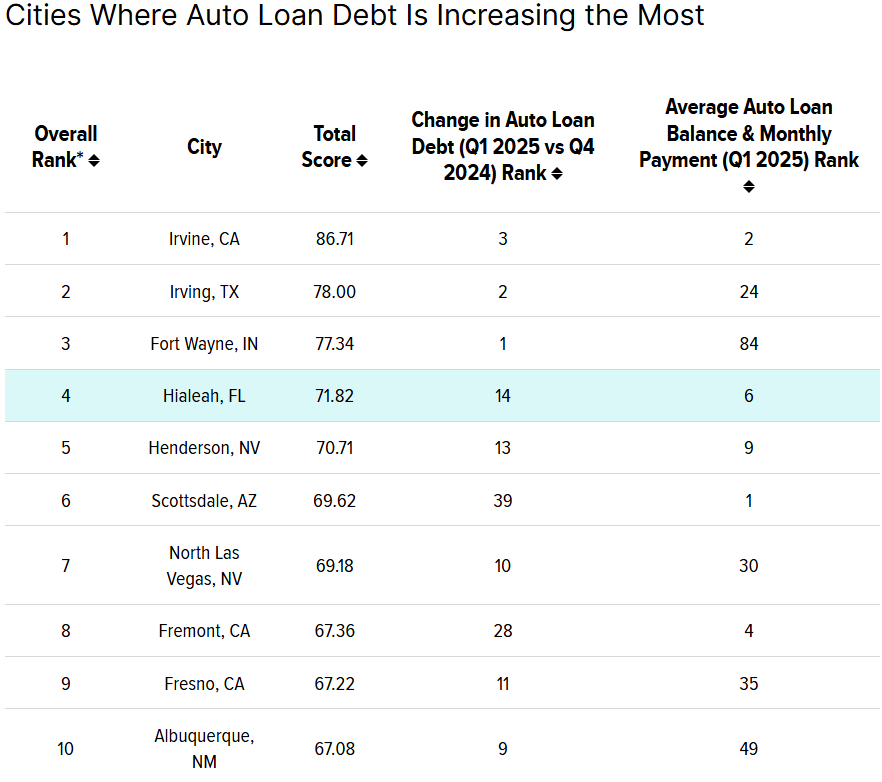
WalletHub has identified the cities where auto loan debt is growing the fastest and those where the increases are more modest by examining proprietary consumer debt data.  Here are the findings:

Cities with the Most Auto Loan Debt

Hialeah ranks in the Top 5 cities where auto loan debt is increasing the most. Miami comes in at #43 on the list. In most of the Top 10 cities on the list, this extra debt is a bad sign because those cities tend to have high debt delinquency rates and a lot of people experiencing financial distress.

Click here to read more.

If you have questions on this topic or are in a financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can advise you of all of your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys’ help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild and recover. The day you hire our firm, we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Foreclosures, Housing Market Trends

Florida Foreclosures Spike in the Aftermath of Last Year’s Hurricane Season

Florida led the nation in foreclosures in 2024, and all signs point to a continuation in the trend. A report by property data firm ATTOM shows that Lakeland ranked No. 1 nationwide for the most filings in 2024, with one in every 172 homes foreclosed on.

After a six-month period of decline, foreclosure filings abruptly increased in October, revealing the impact back-to-back hurricanes had on the market.

Hillsborough, Broward, Miami-Dade and Orange counties had the most foreclosures in Florida. Among U.S. metro areas with populations greater than 1 million, Orlando, Jacksonville and Miami had the first, third and fourth highest rates in the nation.

Foreclosures can oftentimes be a precursor to bankruptcy, and both have risen dramatically over the last 12 months.

Several major Florida metros ranked in the top 10 U.S. cities whose residents have the highest levels of financial distress. Tampa ranked No. 8, while Jacksonville, Orlando and Miami ranked third, sixth and ninth.

Click here to read more.

Choosing the right attorney can make the difference between keeping your home or losing it in foreclosure. A well-qualified Miami foreclosure defense attorney will not only help you keep your home, but they will be able to negotiate a loan that has payments you can afford. Miami foreclosure defense attorney Timothy Kingcade has helped many facing foreclosure alleviate their stress by letting them stay in their homes for at least another year, allowing them to re-organize their lives. If you have any questions on the topic of foreclosure, please feel free to contact me at (305) 285-9100. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
REMEMBER: In Florida, the homeowner has rights when it comes to foreclosure! But do not delay.

Foreclosure Defense, Foreclosures

US Foreclosures Down 13 Percent in Q3 2024

A total of 87,108 U.S. properties had foreclosure filings in the third quarter of 2024, representing a 2 percent decrease from the previous quarter and a 13 percent decline from the same period last year.  This is according to ATTOM’s newly released Q3 2024 U.S. Foreclosure Market Report.

States with over 1,000 foreclosure starts in Q3 2024 that saw the largest annual drops included North Carolina (down 44 percent), Georgia (down 29 percent), Maryland (down 22 percent), New Jersey (down 20 percent), and South Carolina (down 19 percent).

Among major metropolitan areas (population of 200,000 or more), those with the most foreclosure starts in Q3 2024 were Miami, FL (2,142), New York, NY (3,776), Chicago, IL (3,231), Los Angeles, CA (2,166), and Houston, TX (1,791).

The Highest Foreclosure Rates were seen in Florida, Illinois, and Nevada.

Nationwide, one in every 1,618 housing units had a foreclosure filing in Q3 2024. States with the highest foreclosure rates were Florida (one in every 971), Illinois (one in every 904 housing units), Nevada (one in every 922), Delaware (one in every 1,060), and South Carolina (one in every 1,069).

Among the 224 metropolitan statistical areas with populations of at least 200,000, the highest foreclosure rates in Q3 2024 were recorded in Lakeland, FL (one in every 610 housing units), Orlando, FL (one in every 859), Provo, UT (one in every 647), Macon, GA (one in every 649), Columbia, SC (one in every 663), and Atlantic City, NJ (one in every 766).

Click here to read more.

REMEMBER: In Florida, the homeowner has rights when it comes to foreclosure! But do not delay.

Choosing the right attorney can make the difference between keeping your home or losing it in foreclosure. A well-qualified Miami foreclosure defense attorney will not only help you keep your home, but they will be able to negotiate a loan that has payments you can afford. Miami foreclosure defense attorney Timothy Kingcade has helped many facing foreclosure alleviate their stress by letting them stay in their homes for at least another year, allowing them to re-organize their lives. If you have any questions on the topic of foreclosure, please feel free to contact me at (305) 285-9100. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Related Resource:
Kingcade & Garcia, P.A.- Foreclosure Defense (youtube.com)

Legal Awards

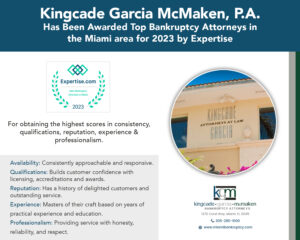
Kingcade Garcia McMaken Awarded ‘Best Bankruptcy Lawyers in Miami’ for 2023

MIAMI (February 28, 2023) — The Miami-based bankruptcy law firm of Kingcade Garcia McMaken has been awarded one of the ‘Best Bankruptcy Lawyers in Miami’ for 2023, by Expertise for obtaining the highest scores in consistency, qualifications, reputation, experience & professionalism.

Expertise Award Best Bankruptcy Attorneys 2023

“We are extremely honored to have received this award,” says Founding Partner and Managing Shareholder, Timothy S. Kingcade. “In today’s competitive legal environment, clients have an increasing number of options when choosing an attorney. It is important that clients and potential clients know how serious we take quality customer service and business ethics. This is a true testament to the commitment we have to our clients and the standards we uphold as a law firm.”

Credit Card Debt

U.S. Cities with the Least-Sustainable Credit Card Debt

High interest rates and high inflation are making it harder than ever to pay down credit card debt. American consumers started the year with over $1 trillion in outstanding credit card debt.

According to a recent study, the average U.S. household has over $8,900 in credit card debt, which is up 4.5 percent (4.5%) from last year. Consumers in certain cities seem to struggle more than others. This fact was recently documented in a study produced by personal finance website, WalletHub, listing which American cities had the least sustainable credit card debt.

Foreclosure Defense, Foreclosures

Florida Homeowners Struggle to Pay PACE Home Improvement Loans

Florida homeowners who have financed home improvements through help of an energy loan program are now struggling to pay back those debts. The program, named Property Assessed Cleaning Energy, also known as PACE, is a financing program used to fund improvements to property owner’s homes in Florida over the past three years.

PACE is offered only in three states throughout the country. For some South Floridians, the PACE program has been a blessing, but it has unfortunately ended up being more of a curse for many of them as they struggle to pay back their loans. This money meant the ability to install a new roof, solar energy systems, an air conditioning system or even hurricane-resistant impact windows. Through PACE, all of this would be financed with nothing down and no credit check. The applicant simply would need to show that he or she had equity in the home, had a good history of making mortgage payments on time, and could show that he or she had enough money to make payments on the PACE loan.

Bankruptcy Law

How to Time Your Bankruptcy Filing

Deciding when to file for bankruptcy can be a complicated one. Many times, it makes sense to delay filing for bankruptcy, while other times it makes sense to file right away.  In some situations, people are able to work out a plan to pay off their debt without having to file at all. If someone is struggling with making that determination, a bankruptcy attorney can help talk that person through his or her life situation and can help the individual decide when a good time would be for filing for bankruptcy.

Modifying a Mortgage

Bankruptcy is often used as a means of delaying foreclosure. In a Chapter 13 bankruptcy case, a bankruptcy filing will often allow the person to catch up on past-due payments while continuing to make current ones. However, sometimes a mortgage modification may be all the filer needs to hold onto his or her home. If the person files too quickly, he or she may have a harder time obtaining a modification of the mortgage. In fact, once a bankruptcy case has been filed, many lenders will not even talk to the borrower in terms of negotiations over the mortgage. If the borrower is anticipating a mortgage modification, it may be best to wait before filing for bankruptcy.

Income Qualifications

If someone is wanting to pursue a Chapter 7 bankruptcy case, he or she will need to pass the “means test” requirements set by the bankruptcy courts in Florida. If the filer’s income is too high, he or she will be prevented from pursuing a Chapter 7 liquidation bankruptcy case. Not passing the means test does not necessarily mean the person cannot pursue any type of bankruptcy. The filer may still qualify for a Chapter 13 bankruptcy plan, which requires him or her to repay a portion of the qualifying debts over a three to five-year period. The means test calculates the person’s income over a period of several months. Therefore, if the person’s income has dropped recently, he or she may still be able to qualify for Chapter 7 by holding off on filing for a few months.

Keeping Certain Property

Many times, the filer may have certain property that he or she would lose in a Chapter 7 bankruptcy case, such as an incoming tax refund. If the case is filed too soon, that tax refund may be liquidated and used to pay off certain debts. If the potential filer expects a large income tax refund, he or she may wish to hold off on filing for bankruptcy temporarily and use that money to pay for living expenses over the course of a few months before filing. However, make sure that the expenses being paid with this refund are for necessities and not luxury items. Otherwise the bankruptcy trustee may see the filer as trying to conceal or hide this income before filing. Also, this situation only matters for property that does not fall under an exemption, including the personal property exemption for Florida filers.

New Incoming Debts

If the filer anticipates some additional debts coming in the near future, it may also be wise to hold off on filing for bankruptcy. For most cases, a Chapter 7 bankruptcy case will only liquidate debts the filer has as of the date the petition was filed. Any debt that is incurred after the date of filing will stay with the filer after discharge. If the filer anticipates a major medical expense that will result in debt or necessary home improvement expense, it may be best to wait for filing until after that expense has been incurred, making it possible for that debt to be discharged.

If you have questions on this topic or are in financial crisis and considering filing for bankruptcy, contact an experienced Miami bankruptcy attorney who can advise you of all of your options. As an experienced CPA as well as a proven bankruptcy lawyer, Timothy Kingcade knows how to help clients take full advantage of the bankruptcy laws to protect their assets and get successful results. Since 1996 Kingcade Garcia McMaken has been helping people from all walks of life build a better tomorrow. Our attorneys’ help thousands of people every year take advantage of their rights under bankruptcy protection to restart, rebuild and recover. The day you hire our firm, we will contact your creditors to stop the harassment. You can also find useful consumer information on the Kingcade Garcia McMaken website at www.miamibankruptcy.com.
Related Resources:

https://www.nolo.com/legal-encyclopedia/file-bankruptcy-or-wait-29955.html